 Stormischeer Insurance
Life coverage
Term and permanent life plans that replace income, fund education, and settle final expenses without forcing loved ones to guess your intentions.
View featured life policy
Each line of coverage starts with a conversation about who depends on you, what you own, and how you move through the world. These four foundations cover most households we serve.
Term and permanent life plans that replace income, fund education, and settle final expenses without forcing loved ones to guess your intentions.
View featured life policy
Individual and group health options with transparent networks, preventive care, and guidance when specialists or ongoing treatment enter the picture.
Explore health services
Dwelling, contents, and liability limits tuned to rebuild costs, detached structures, and the personal property you would struggle to replace quickly.
Home service detail
Liability, collision, and comprehensive combinations for daily drivers, shared vehicles, and fleets that need consistent claims handling.
See auto pricing tiersWe opened Stormischeer to give policyholders a steadier experience from quote through renewal. Too many people discover coverage gaps only after a kitchen fire, a medical diagnosis, or a highway collision. Our process maps your assets, dependents, and contractual obligations first, then aligns carrier products to those facts.
Licensed advisors stay with the same clients across life events—marriage, new homes, business launches, and retirement transitions—so documents stay current and beneficiaries stay accurate. We maintain plain-language summaries alongside official policy jackets, and we rehearse claims steps before emergencies arrive.
Business clients receive the same attention: we review general liability, property, workers compensation where applicable, and professional lines that match how you actually deliver services.
Learn more about us
Six specialists coordinate life, health, property, auto, and commercial lines. Each maintains continuing education on carrier rule changes and claims best practices.
Life & estate planning
Auto & fleet
Health benefits
Claims advocacy
Home & property
Business coverage
18+
Years serving policyholders
12k
Active policies managed
96%
Renewal retention rate
48hr
Average first claim response
Life quotes estimate benefit amounts, term lengths, and optional riders such as accelerated death benefits or child term riders. Share household income, existing group coverage, and outstanding debts so we can model realistic replacement targets.
Home quotes reflect rebuild value, contents limits, liability umbrellas, and optional endorsements for water backup or scheduled valuables. Tell us about year built, roof age, and safety devices to refine premiums.
Auto quotes combine liability limits, collision and comprehensive deductibles, and usage details for commuters or business drivers. List vehicles, primary drivers, and annual mileage for accurate tiers.
Rebuild costs follow construction and material trends, not market resale prices. We review square footage, finishes, and local builder estimates during annual reviews. If you renovate kitchens or add rooms, notify us before renewal so the dwelling limit rises with the new value.
Check for injuries, move to a safe location when possible, and exchange driver and policy information. Photograph damage, road conditions, and license plates. Contact us promptly so we can open a claim, arrange towing if needed, and explain rental reimbursement when your policy includes it.
Most health plans restrict network changes to open enrollment unless you experience a qualifying life event such as marriage, birth, or loss of other coverage. We help document qualifying events and submit carrier forms so new networks begin on the correct effective date.
General liability and workers compensation rules depend on where work occurs and how equipment is owned. We map home offices, client sites, and company laptops to ensure liability and injury coverage follow your team. Professional liability may also need updates when services cross borders digitally.
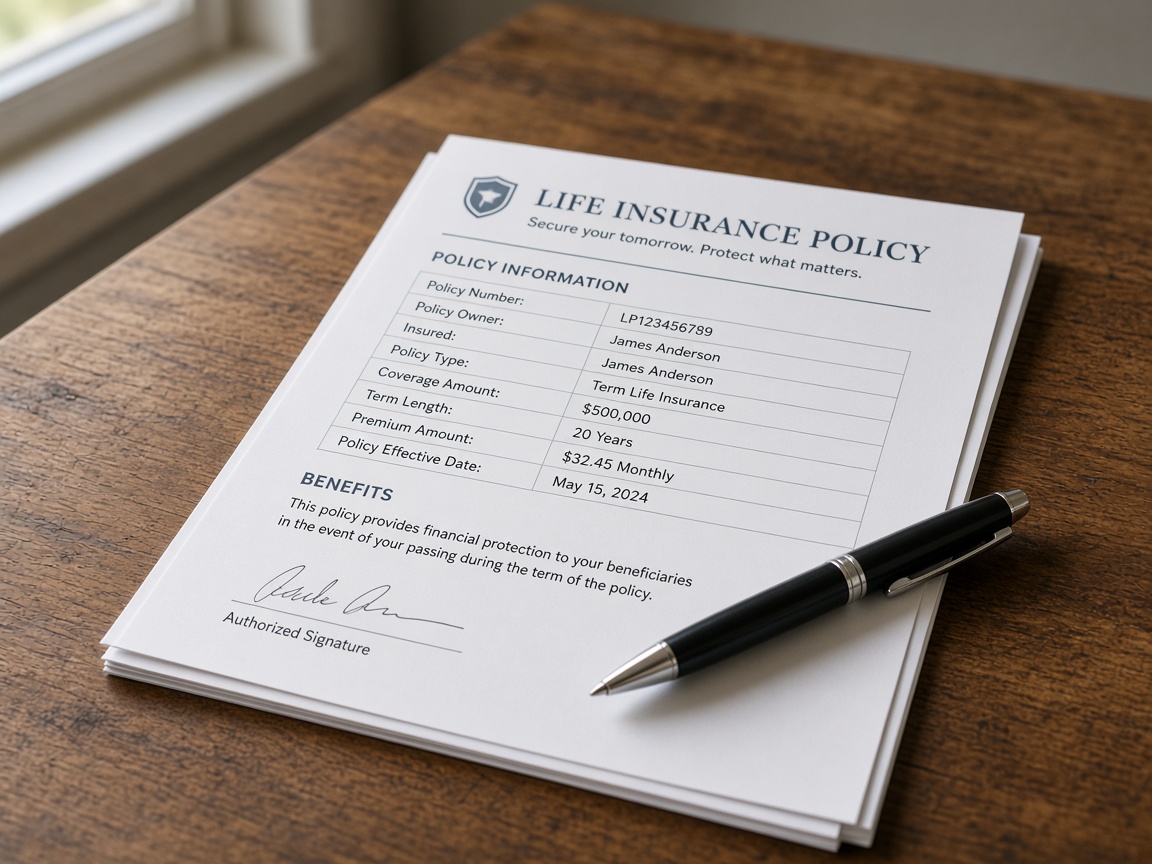
Keep primary and contingent beneficiaries aligned with trusts, divorce decrees, and business buy-sell agreements.
Balance premium savings against the emergency fund you can deploy after a covered loss.
Room-by-room lists, serial numbers, and photo backups reduce disputes after theft or fire.